Discover the Workings of Credit Card Processing
📅 2026 Update: Key Changes in Credit Card Processing
Since the original article was published, several important changes have taken place in credit card processing and consumer protections. The landscape is shifting, especially regarding late fees and the costs associated with credit card transactions. The details below highlight these updates and their implications for consumers.
📉 New Credit Card Late Fee Cap
In March 2024, the Consumer Financial Protection Bureau (CFPB) finalized a rule to reduce the typical credit card late fee from $32 to $8. This change aims to save consumers over $10 billion each year. However, as of March 2024, litigation has stayed the cap's implementation.
📜 Proposed Credit Card Fairness Act
In January 2026, Senators Cory Booker, John Fetterman, and Tammy Baldwin introduced the Credit Card Fairness Act. This act aims to codify the $8 late fee cap into law. If passed, it would provide a permanent reduction in late fees for consumers.
💵 Increased Exemption Threshold
The CFPB has adjusted the exemption threshold for certain credit card fees based on the Consumer Price Index for All Urban Consumers (CPI-W). Effective January 1, 2026, this threshold rose from $71,900 to $73,400. This change affects which fees fall under specific regulations.
🏦 Clarification on Bank Fees
In April 2026, the Office of the Comptroller of the Currency (OCC) clarified that national banks can charge non-interest fees, including interchange fees, regardless of who sets them. This ruling impacts how banks manage and disclose fees associated with credit card transactions.
📌 Key Points Summary
- 📉 Late fees reduced to $8 but facing legal challenges.
- 📜 Credit Card Fairness Act proposed to make this cap law.
- 💵 Exemption threshold increased to $73,400.
- 🏦 Banks can charge various fees as clarified by the OCC.
- Consumers should stay informed about these changes.
💡 Tips for Managing Credit Card Fees
Reviewing your financial situation is essential. Always consider discussing your specific circumstances with an attorney for tailored insights.
📋 Understand Your Rights
Consumers have the right to opt out of new terms if a credit card issuer changes account conditions. Make sure to notify the issuer within 45 days before the changes take effect.
📊 Keep Track of Fees
Stay informed about the fees associated with your credit card. This includes understanding late fees and any additional charges that may apply.
🕒 Pay on Time
To avoid late fees, set reminders for payment due dates. Paying on time not only helps you avoid penalties but also positively impacts your credit score.
💳 Compare Processing Fees
If you are a business owner, compare credit card processing fees from different providers. Look for competitive rates to minimize costs.
📞 Use Free Resources
Utilize resources from the Consumer Financial Protection Bureau (CFPB) and the National Credit Union Administration (NCUA). They offer free information and assistance regarding credit card issues, fees, and rights.
🏆 Free Options Ranked by User Reviews (2026)
No national paid services have met the review threshold for this topic. Instead, here are some valuable free government and nonprofit resources.
🥇 1. Consumer Financial Protection Bureau (CFPB)
The CFPB provides free resources and assistance to consumers facing credit card issues. They help with understanding fees, disputing charges, and managing debt. This service is beneficial for anyone looking to navigate credit card terms and conditions.
🥈 2. National Credit Union Administration (NCUA)
The NCUA offers guidance on non-interest charges and fees from federal credit unions. They help consumers understand their rights and options regarding credit unions, making it easier to handle credit card-related concerns.
🥉 3. Federal Trade Commission (FTC)
The FTC requires businesses to disclose additional fees, including credit card surcharges, upfront. This regulation helps consumers make informed decisions about their purchases and avoid unexpected costs.
🔎 Check Before Paying for Help
- 🏦 Verify the legitimacy of any service.
- 📄 Look for reviews and ratings from other users.
- 💬 Understand what fees may apply.
- 📋 Confirm the services offered match your needs.
❓ Frequently Asked Questions
❓ What is the current late fee cap for credit cards?
As of 2026, the late fee cap is $8. However, legal challenges are currently affecting its implementation.
❓ How can I dispute a credit card charge?
You can dispute a charge by contacting your credit card issuer directly. They typically have a process for handling disputes outlined in your cardholder agreement.
❓ What should I do if I miss a payment?
If you miss a payment, contact your issuer immediately. They may offer options to help you manage the situation, but expect to pay the late fee.
❓ How often do credit card fees change?
Credit card fees can change based on various factors, including regulations and company policies. It is essential to review your cardholder agreement regularly.
❓ What is the purpose of interchange fees?
Interchange fees are charges paid by merchants to card-issuing banks for processing transactions. They help fund credit card rewards and cover transaction costs.
❓ Are there any free resources for credit card help?
Yes, the CFPB and NCUA offer free resources and assistance for consumers dealing with credit card issues.
⚖️ Recent Court Cases Related to Credit Card Processing
Several recent court rulings may influence credit card processing and consumer protection laws. These decisions are critical as they shape the rights and fees associated with credit cards.
- Texas court dismisses appeal due to unpaid feesTexas Court of Appeals, 9th District (Beaumont) · May 28, 2026
- Court dismisses appeal in credit card breach caseCourt of Appeals of Georgia · May 29, 2026
- Hawaii Court Dismisses Central Pacific Bank's AppealHawaii Intermediate Court of Appeals · May 29, 2026
- Court reverses dismissal in U.S. Bank foreclosure caseAppellate Division of the Supreme Court of the State of New York · May 19, 2026
For more recent rulings, you can browse more rulings on the news page.
End of October 2026 Update
What is a Credit Card?
A credit card is an alternative payment method to
cash, which enables a consumer to purchase goods or services on credit. Credit
cards are issued by financial institutions to those individuals who they deem
as fit or credit-worthy. The ability to obtain a credit card and the subsequent
rates or fees attached to the issuance is based primarily on an individual’s
credit history and score.
The lower the score, the lower chance to receive a
credit card. If a financial institution grants a card to an individual with a
low score, it will invariably be met with high interest rates and complicated
terms.
The interest rates and fees attached to the
issuance are dependent on the individual’s expected ability to repay their
borrowed funds. When an individual purchases goods on a credit card they are
required to reimburse the issuing company the amount spent. If the full balance
is not paid each month the interest is applied and carried over to the
following billing period.
How does Retail Credit Card Processing Work?
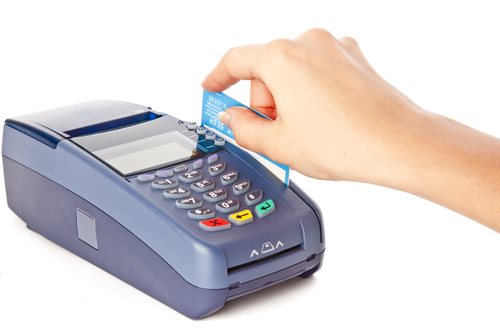
When an individual purchases a good or service
from a retail store with a credit card, they simply slide the card into a
machine. Each credit card is equipped with a magnetic strip on the back. When
sliding a credit card through the machine, the magnetic strip will relay the cardholder’s
information to the retail outlet’s point-of-sale system. This step of credit
card processing enables the cashier to integrate the individual’s information
into their transaction.
In addition to using a machine to initiate the
credit card processing through the magnetic strip, an employee at the retailer
can also type the card information (the credit card number on the front of the
card) into their point-of-sale system. This form of credit card processing is
utilized for online purchases or for those transactions that do not involve a
card reader.
All retailers that initiate credit card processing
must sign up for a service that is linked with a merchant provider. Seller
transaction credit card processing systems send captured credit card data,
along with the data linked to the transaction, directly to the merchant account
provider.
card network interchange. This intermediary then connects banks and credit card
providers together to finalize the transaction.
Network Interchange involved in Credit Card
Processing
The merchant account must first route the
information through the network interchange to the holder’s institution. The
institution then checks the card’s balance against the transaction amount and
either authorizes or denies the payment.
The next step in credit card
processing involves the credit card provider routing the information back to
the merchant account. When the information is relayed, the transaction will
either be rejected or finalized. In full, credit card processing takes as
little as two or three seconds.
Once the authorization for approval or denial of
payment has been received, the merchant notifies the seller of the result, who
then will notify the buyer. If the transaction involved in the credit card
processing is authorized, the merchant account provider sends the transaction
information back through the network interchange to the seller, who then
requests the funds to be transferred from the buyer’s credit card provider.