The Importance of Credit Scores
📅 2026 Update: Changes in Credit Scores and Services
Since the original article was published, there have been notable changes in how credit scores are calculated and assessed. New scoring models aim to provide a broader view of creditworthiness. Readers can find the earlier article further down the page, where it covers foundational information about credit scores.
📈 Recent Scoring Model Changes
In recent years, two major scoring models have emerged. FICO introduced the FICO Score 10 and 10T in 2024. These models use trended data to give lenders a better understanding of consumer behavior over time.
This means that your credit score may now reflect your spending habits more accurately.
📝 Current Fees for Credit Reports
Under the Fair Credit Reporting Act, consumers can receive one free credit report each year from Equifax, Experian, and TransUnion. Any additional reports typically cost around $10 to $15. It's important to check your credit report regularly to ensure it's accurate and up to date.
🔍 Disputing Errors Made Simple
If you find errors in your credit report, you can dispute them easily. Consumers can contact the credit bureau directly online, by mail, or over the phone. Credit bureaus are required to investigate disputes within 30 days, helping you resolve issues quickly.
📊 Understanding Credit Score Ranges
Credit scores are categorized as follows:
- Excellent: 750 and above
- Good: 700 to 749
- Fair: 650 to 699
- Poor: Below 650
Lenders may have different requirements based on the type of loan, which could affect your borrowing options.
📌 Key Points to Remember
- 📊 New scoring models offer a broader view of credit behavior.
- 💰 Consumers can get one free credit report annually.
- 🔍 Disputes must be resolved within 30 days.
- 📈 Credit score ranges affect borrowing options and interest rates.
- 🏦 Understanding your credit score is vital for financial health.
💡 Tips for Managing Your Credit Score
Review your credit situation carefully with your attorney.
🏦 Pay Your Bills on Time
Payment history is the most significant factor in your credit score. Timely payments can improve your score by showing lenders that you are responsible with credit.
💳 Keep Credit Utilization Low
Aim to keep your credit utilization below 30%. This means using less than 30% of your available credit, which can positively impact your score.
📝 Check Your Credit Reports Regularly
You are entitled to one free credit report annually from each major bureau. Regular checks can help you spot errors or fraudulent activity early.
🔄 Limit Hard Inquiries
Be cautious about applying for new credit cards or loans. Each hard inquiry can lower your score slightly and remains on your report for up to two years.
📈 Consider Credit Monitoring Services
Using third-party credit monitoring can help you stay informed about your credit status. Services usually range from $10 to $30 per month, providing alerts for changes in your score.
🏘️ Use Diverse Credit Types
Having different types of credit, such as credit cards, auto loans, and mortgages, can help improve your score. Lenders like to see that you can manage various credit forms responsibly.
🏆 Top Credit Services Ranked by User Reviews (2026)
This section highlights services that help consumers improve their credit scores. The data is based on Trustpilot reviews as of October 2026. Ratings can change, and it's important to consider multiple factors when evaluating these services.
🥇 1. Pave
Pave holds a 4.5 star rating. This service is known for its credit score improvement app and credit-building services. However, it is limited to the UK market, which may not suit all users.
🥈 2. Credit Glory LLC
Credit Glory LLC has a 4.4 star rating. It provides credit counseling services and credit repair assistance. Keep in mind that the availability of services can vary by state, so check if they are offered where you live.
🥉 3. MSI Credit Solutions
MSI Credit Solutions has an impressive 4.9 star rating. This service is recognized for its credit counseling and score improvement techniques. Like others, its services may differ depending on your state.
4️⃣ Helping Hands Financials LLC
Helping Hands Financials LLC boasts a perfect 5.0 star rating. They offer credit counseling services and credit repair assistance. As with other services, availability may vary by state.
🆓 Free Government and Nonprofit Help
Consumers can obtain free annual credit reports from the three major bureaus. Nonprofit organizations, like the National Foundation for Credit Counseling, offer free or low-cost credit counseling services, making it easier to get help without added costs.
🔎 What to Compare When Choosing a Credit Service
- 🏆 Trustpilot ratings and review counts
- 📋 Types of services offered
- 🌎 Availability by state or region
- 💰 Pricing and hidden fees
- 📞 Customer support options
❓ Frequently Asked Questions
❓ What is a credit score?
A credit score is a numerical representation of your creditworthiness, typically ranging from 300 to 850. Lenders use this score to assess the risk of lending money.
🕒 How often should I check my credit report?
It's recommended to check your credit report at least once a year. You can obtain a free report annually from each of the three major credit bureaus.
💳 Can I improve my credit score quickly?
While significant improvements can take time, making timely payments and reducing your debt can help increase your score. Avoiding new credit inquiries also contributes positively.
🔄 What are hard inquiries?
Hard inquiries occur when a lender checks your credit report as part of their decision-making process. They can lower your score slightly and stay on your report for up to two years.
🏦 Do I need good credit to get a loan?
Good credit typically increases your chances of getting approved for loans. Some lenders may require a minimum credit score, depending on the type of loan you seek.
🔍 What should I do if I find an error on my credit report?
You can dispute inaccuracies by contacting the credit bureau directly. They must investigate the dispute within 30 days and provide you with results.
⚖️ Recent Cases Related to Credit Scores
Recent court rulings have addressed issues related to credit scores and reporting. These cases often focus on disputes and inaccuracies in credit reports, impacting consumers' financial decisions.
- Florida court denies petition in dispute over legal feesDistrict Court of Appeal of Florida · October 19, 2022
- Florida court rules on property partition and attorney feesDistrict Court of Appeal of Florida · November 16, 2022
- Court Affirms Ruling in Hyman v. U.S. Bank CaseDistrict Court of Appeal of Florida · December 14, 2022
- Florida court denies petition in Ponton v. Colonial Bank caseDistrict Court of Appeal of Florida · February 3, 2023
For more information about recent rulings, visit more rulings on the news page.
End of October 2026 Update
What is a Credit Score?
A credit rating is a statistical analysis of an individual’s credit history. The credit score is delivered as a number based on the individuals debt vs. credit amount. This number is used by numerous lenders (organizations that distribute loans or credit card companies) to determine whether or not they will award an individual or business with a line of credit. In essence, the credit score is the fundamental statistic used to evaluate an individual or entity’s credit worthiness.
There are three agencies that will issue a credit rating: TransUnion, Experian and Equifax. The majority of lenders will evaluate the credit score of two of the three agencies; the credit score is distributed in a report, which will detail the prospective borrower’s credit history.
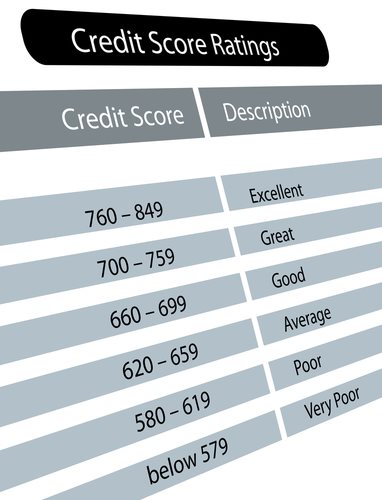
The formula used to determine a credit score is known as FICO. Named after the Fair Isaac Credit Organization (the first company to use credit ratings), this formula will yield a number ranging from 300 to 900. The lower the credit score, the greater the risk of default; an individual with a score that is below 500 is viewed as a risky borrower to most lenders.
The risk in this sense is tied into the borrower’s ability to repay the loan or pay-off his or her credit card. The credit score, thus acts as a gauge to determine a risk of default; ratings closer to 300 are viewed as extremely risky, while those above 800 are viewed as possessing limited to no risk.
The FICO Calculation:
The FICO score is calculated based on the percentage of an individual’s total credit that is currently being utilized, the amount of time an individual has had an open line of credit, the types of credit lines the individual possesses, the amount of past lines of credit the individual has had, and the number of delinquent payments.
Each of these variables contains the following percentage weight to determine one’s credit score: Amount of credit currently utilized (30%), the period of time the lines of credit have been open (15%), the types of credit lines open (10%), the size of past lines of credit (10%) and the number of delinquent payments (35%).
In a general sense, a credit score around 500 is viewed as high risk; this score will generally yield a refusal to lend. If an individual obtains a credit line with a credit score around 500, they will be given a line of credit with high interest rates, exorbitant fees and complicated terms.
A credit score of 800 or above, in contrast, will grant an individual the lowest possible interest rates, small down payments (where applicable) and limited fees. A credit score of around 650 is viewed as safe enough to receive favorable terms; this score will typically be good enough to receive a new line of credit.
How do I view my Credit Score?
The majority of organization offer online access to your credit score. These websites will offer reports from the leading credit agencies and detail why your score may be low. Given the importance of favorable terms and interest rates it is recommended that you view your credit score to ensure that no mistakes have been made.
Often times an individual’s credit score will be lowered because of a forgotten debt or miscalculated payment. In order to raise one’s credit score, they must realize the position they are in. As a result of this, paying a small fee to view your credit score is well worth it.